What is the scope and industry significance of the Forged Grinding Ball Market?
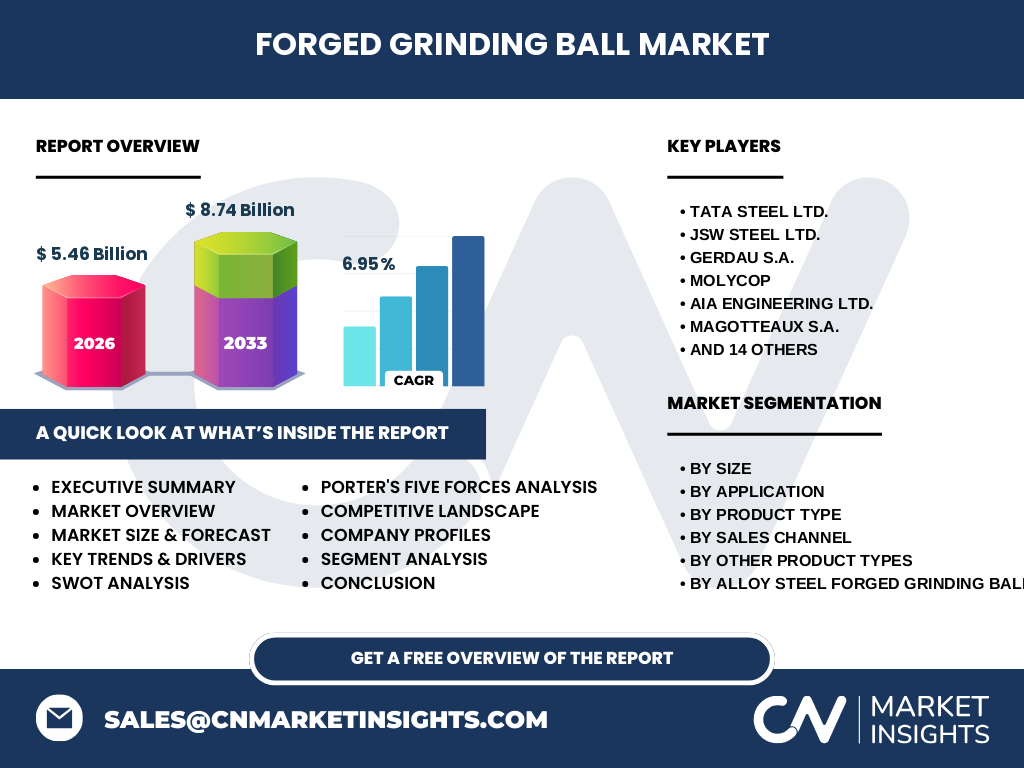
Our analysis indicates that the Forged Grinding Ball Market size stands at $5.46 Billion in 2026, serving as an indispensable consumable in heavy-duty comminution circuits. These high-density steel media drive ore reduction efficiency across global mining hubs, cement kilns, and thermal power generation facilities, dictating baseline operational expenditures for primary resource extractors.
Structural Growth Drivers and Market Restraints
The market is propelled by surging demand for alloy steel forged grinding balls in deep-shaft mining operations targeting lower-grade ores. However, structural restraints such as volatile scrap steel and ferroalloy pricing, alongside stringent environmental compliance mandates enforced by regulatory bodies like the EPA and China's Ministry of Ecology and Environment, challenge margin expansion.
Emerging Industry Trends in the Forged Grinding Ball Sector
The shift toward energy-efficient comminution has accelerated adoption of high-chromium and chromium-molybdenum alloy variants. Industry leaders are leveraging proprietary heat-treatment technologies to minimize wear rates, reducing mill downtime for tier-one mining operations dependent on continuous throughput at major processing plants.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-induced supply chain bottlenecks and logistical hurdles across key maritime shipping lanes initially disrupted raw material acquisition. The subsequent recovery trajectory has been robust, fueled by aggressive fiscal stimulus directed toward global infrastructure projects and an unprecedented surge in base metal extraction.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is defined by consolidation among tier-one multinational giants such as Molycop, Magotteaux S.A., and AIA Engineering Ltd. These heavyweights maintain pricing power through backward integration and localized manufacturing footprints, competing aggressively against agile regional specialists like Shandong Huamin and Energosteel.
Executive Summary of Key Findings
Our comprehensive assessment highlights a robust expansion trajectory, projecting the Forged Grinding Ball Market to reach $8.74 Billion by 2033 at a 6.95% CAGR. Strategic success requires continuous metallurgical innovation, direct supply contracts with major mining conglomerates, and stringent quality control aligned with ISO standards.
Long-Term Market Forecast from 2027 to 2033
Based on our research, steady volume consumption across emerging economies will sustain an accelerated growth momentum between 2027 and 2033. This expansion is underpinned by rising mineral extraction requirements and the continuous modernization of cement manufacturing plants seeking wear-resistant media solutions.
Segmentation Analysis and Product Role
Segmentation spans multiple dimensions: By Size (Below 50mm, 50–100mm, Above 100mm), By Product Type (Alloy Steel, Carbon Steel, Stainless Steel), By Application (Mining, Cement, Thermal Power, Chemical), and By Sales Channel (Direct Sales, Distributors, Online). Each category plays a distinct role in balancing impact resistance, hardness depth, and mill throughput efficiency.
Regional Market Analysis and Geographic Performance
Geographic distribution heavily favors Asia-Pacific, driven by vast mining and cement manufacturing clusters in China, India, and Australia. Meanwhile, Latin America exhibits exceptional growth dynamics due to intensive copper and iron ore extraction activities managed by major multinational mining houses operating near key Pacific ports.
In-Depth Regional Review
The North American market prioritizes technological sophistication, favoring high-chromium alloy variants that extend relining intervals in hard-rock operations. Conversely, the EMEA region balances stringent EU environmental regulations with high-volume industrial consumption across Eastern European and African mineral belts.
Strategic Positioning of Leading Companies
Industry participants deploy distinct strategic postures: Tata Steel Ltd. and JSW Steel Ltd. leverage captive raw material sources, while specialized innovators like ME Elecmetal and Scaw Metals Group focus on customized digital mill optimization services to lock in long-term enterprise supply agreements.
Porter's Five Forces Analysis of Competitive Pressures
Our analysis indicates moderate-to-high supplier power due to fluctuations in raw energy and steel billet costs, offset by intense rivalry among established grinding media manufacturers. The threat of substitution remains low given the unmatched impact toughness of forged steel over traditional cast alternatives.
SWOT Analysis of the Forged Grinding Ball Industry
Strengths include superior microstructural integrity from advanced forging techniques. Weaknesses stem from high energy consumption during production. Opportunities lie in green-steel initiatives, while threats involve unpredictable raw material tariffs and geopolitical trade disruptions affecting cross-border logistics.
Value Chain Analysis from Raw Materials to End-Users
The value flow originates with scrap metal and alloy additive suppliers, transitions through induction melting and automated forging press lines, and culminates in heavy industrial mills. Managing logistical efficiency from factory floor to remote mining sites is critical for preserving gross operating margins.
Investment Insights and High-Potential Areas
High-potential capital allocation targets automated, low-emission forging facilities and proprietary alloy formulations designed for ultra-deep mining operations. Investors should prioritize enterprises exhibiting strong direct-to-customer relationships with tier-one global mining conglomerates.
Conclusion and Key Takeaways
The Forged Grinding Ball Market industry trends signal a maturation phase centered on metallurgical performance and supply chain resilience. Manufacturers adopting sustainable, low-carbon production processes will capture outsized market share as environmental regulations tighten globally.
Research Methodology and Data Triangulation
Baseline estimates are meticulously triangulated by combining proprietary customs trade registry data, primary stakeholder interviews with C-suite executives across major production hubs, and secondary macroeconomic indicators from international mining and metallurgical associations.
Scope of the Report and Coverage Parameters
This report encompasses a comprehensive global evaluation of the forged grinding ball sector, analyzing volume consumption and value metrics across specified size tiers, product formulations, and end-use applications, with historical validation points leading into the 2027-2033 forecast period.
Recent Developments and Strategic Moves
Recent strategic initiatives include capacity expansions by Iraeta Energy Equipment and Longteng Special Steel, alongside R&D partnerships focused on eco-friendly quenching fluids. These moves reflect an industry-wide push toward operational efficiency, carbon footprint reduction, and enhanced wear resistance.